

The Orthopedic Surgeon Guide to Medical Malpractice vs. E&O Insurance
Every orthopedic practice faces two fundamentally different types of risk. One involves a patient who suffers physical harm during treatment. The other involves financial, regulatory, or privacy harm that has nothing to do with the quality of clinical care. Understanding that distinction is the key to a Medical Professional Liability (MPL) strategy that actually protects your practice.
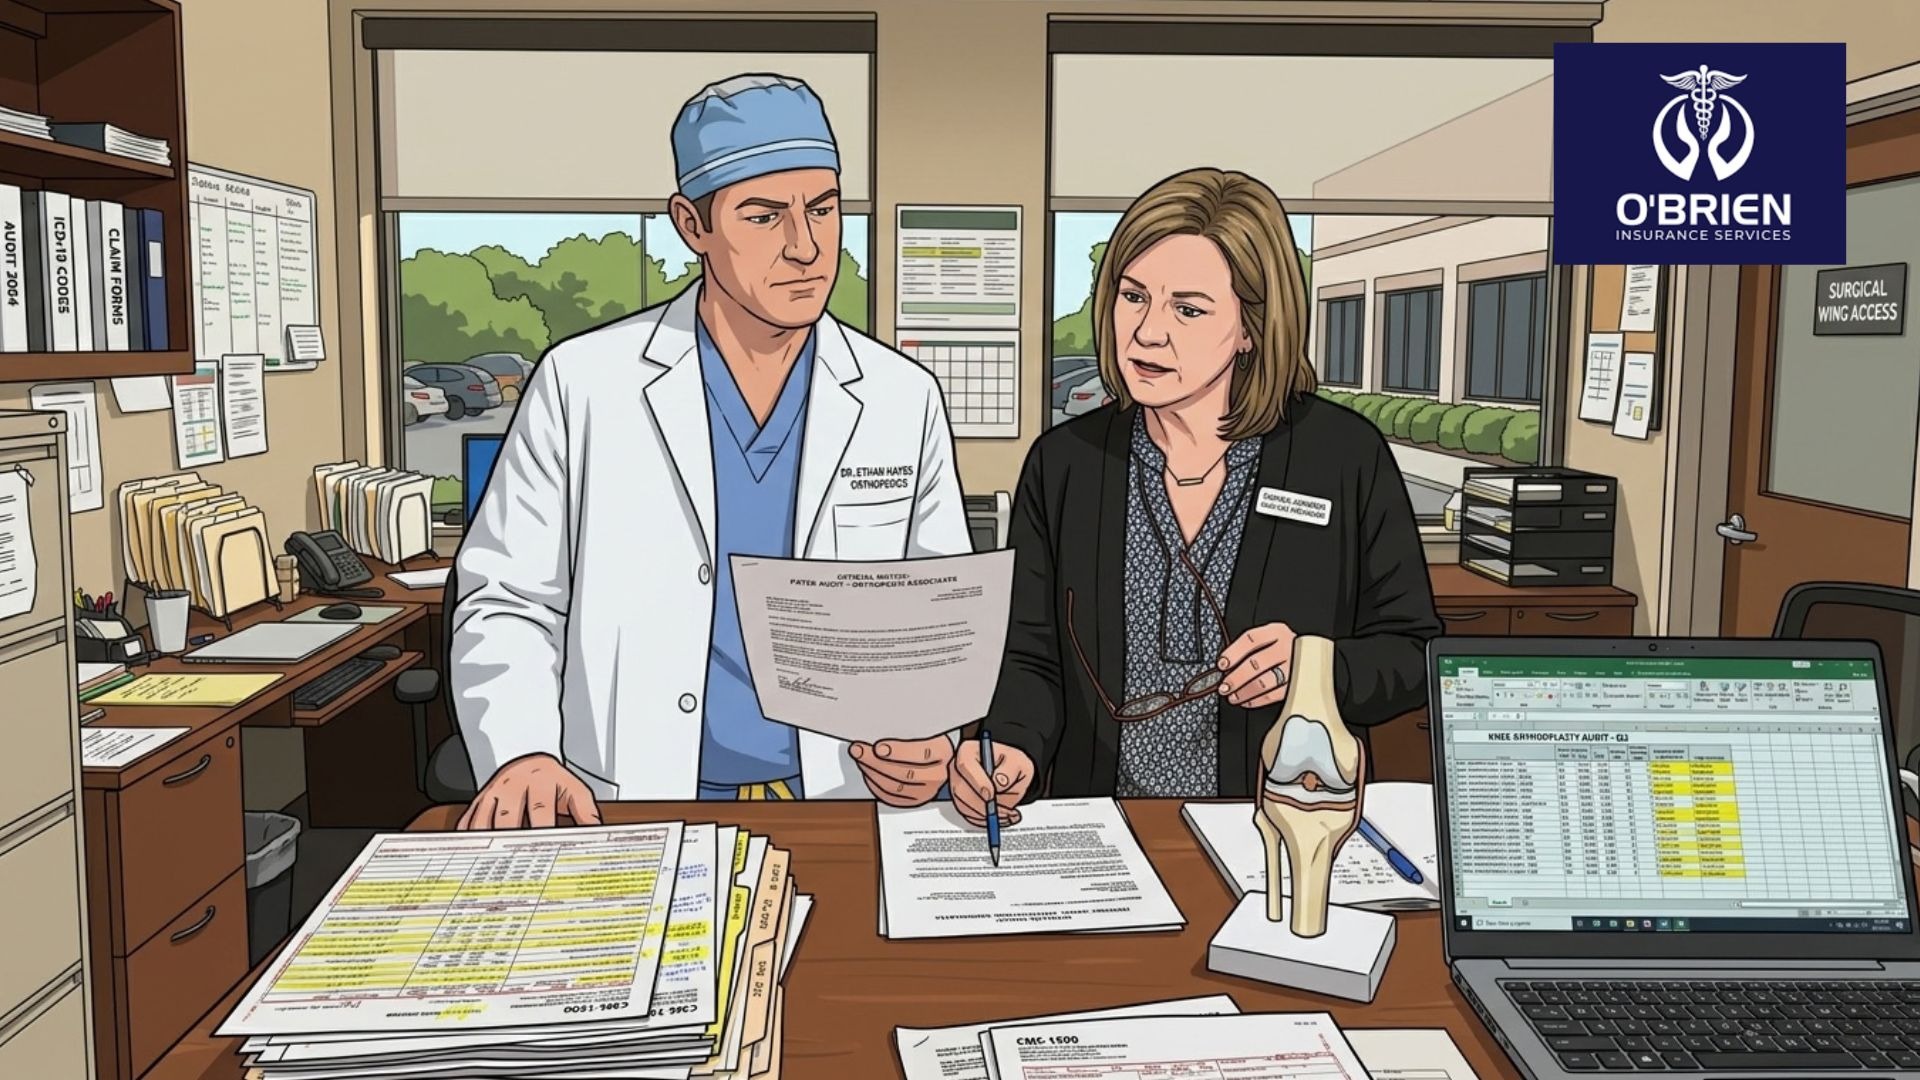
You operate on a full schedule all week, and on Monday a letter from a payer is waiting. They're auditing months of your joint replacement claims over coding discrepancies. No patient was harmed and no procedure went wrong, yet you're now facing repayment demands and legal bills.
And the risky part?
the malpractice policy you have right now may not have the coverage required for any of this. Knowing where one policy stops and another starts is the job of a coverage expert, and I will show you how to get it right the first time.
This guide explains the differences between Medical Malpractice Insurance for orthopedic surgeons and errors and omissions insurance for medical groups, where they intersect, and how to make sure your Orthopedic Practice Medical Professional Liability Insurance program is complete.
Two Types of Risk: A Simple Framework
Think of MPL as an umbrella over your whole practice, with two branches beneath it:
• Medical malpractice responds when a patient claims they were physically harmed by clinical care.
• Medical errors and omissions (E&O) responds when someone claims financial or regulatory harm from your practice's business operations.
Both are sold within an orthopedic practice medical professional liability program, which is why they're so often confused. But they respond to different triggers, and assuming one covers the other can leave you exposed. Understanding medical E&O vs medical malpractice insurance is a practical necessity, not an academic exercise.
Medical Malpractice | Medical E&O | |
Type of harm | Bodily injury | Economic loss |
Typical claimant | Patient or family | Patient, payer, or third party |
Common triggers | Wrong-site surgery, missed diagnosis, prescription errors | Billing errors, HIPAA breaches, IMEs, expert testimony |
Area of practice | Clinical care | Administrative, consulting, operational |
Coverage need | Often mandated by state medical boards | Essential for consulting, IME, or expert witness work |
Medical Malpractice Coverage
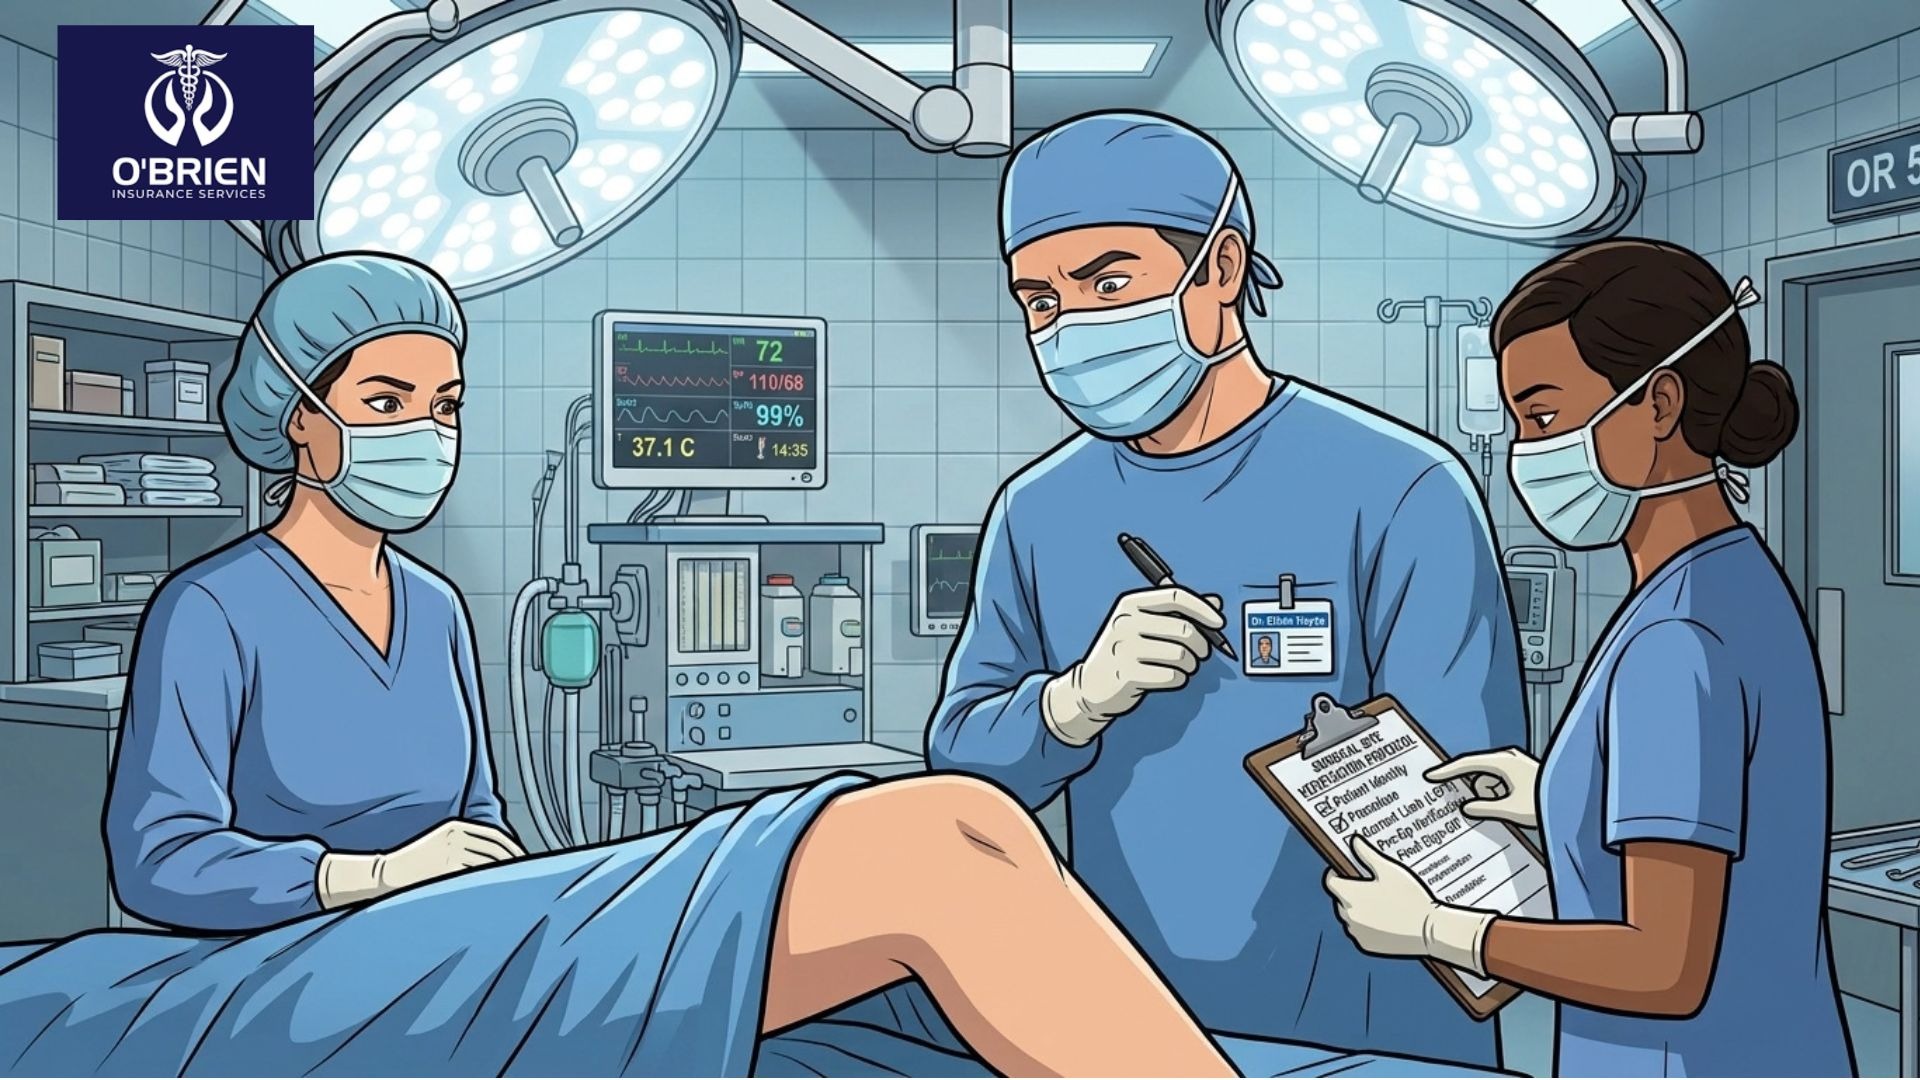
The medical malpractice insurance must protect the orthopedic surgeon when patients allege physical injury or death from treatment. The triggers are clinical:
• Surgical negligence / wrong-site surgery: a procedure on the wrong limb, or an error that causes lasting harm
• Delayed or missed diagnosis: failing to catch a fracture or infection in time
• Prescription errors: the wrong medication, dosage, or interaction
• Improper post-operative care: complications from inadequate follow-up
The claim usually comes from the patient or their family, and coverage funds your legal defense and any damages if you're found liable. Because state medical boards frequently mandate it, this coverage is a license requirement for most orthopedic surgeons, not a choice.
Error & Omission Coverage
Medical E&O insurance, sometimes called administrative professional liability healthcare coverage, responds to allegations of economic loss rather than physical harm. The triggers are operational:
• Billing and coding errors: incorrect claims that cost patients or payers money
• HIPAA privacy breach exposure: unauthorized release of patient information
• Independent Medical Evaluations (IME): claims that an assessment caused financial harm
• Expert witness testimony: allegations that evidence presented was negligent or misleading
E&O coverage addresses your practice’s business aspect, including the administrative issues, and operations-related activities. Thisinsurance is especially important for practices that consult, perform IMEs, or offer expert testimony. It also matters for individual physicians doing such work outside their patient-care role.
The Gray Areas: Consulting, IMEs, and Expert Witness Work
Surgeons who perform IMEs or serve as expert witnesses is exposed to a more complicated landscape, and medical errors and omissions consulting coverage exists for exactly this reason. Say you perform an IME for an insurer, and the patient later claims the evaluation was flawed and led to a denied claim. There's no bodily injury, so it isn't a malpractice claim, but you would still need expert witness liability insurance for doctors to defend it.
Regulatory defense coverage, which protects practitioners facing licensing board investigations, is often included in comprehensive E&O policies but may be excluded from basic malpractice policies. If your practice does any consulting, evaluation, or expert witness work, confirm your program includes E&O protection.
Ancillary Services, Ancillary Risks
Modern orthopedic practices offer far more than surgery, and each added service brings its own exposure. Orthopedic clinics must rely on the right ancillary service liability insurance that comfortably address the following:
• X-ray Imaging and radiation safety standards. Compliance to this regulatory standard demands routine safety checks on equipment, alongside meticulous documentation, and patient protection. Failure in this regard can prompt severe claims and regulatory sanctions. Imaging also generates patient records, so confidentiality and handling of image data belong in your risk-management procedures.
• Blood and tissue laboratories. Tissue sample handling and contamination risk demand strict lab standards and data protocols. A contaminated culture or sample that has been labelled incorrectly can cause serious liability issues.
• Physical therapy. Physical therapy progress documentation is both a care record and a liability shield. Gaps in documenting patient progress, adherence to care standards, or communication between providers invite claims.
Occupational, Regenerative, and Sports Medicine
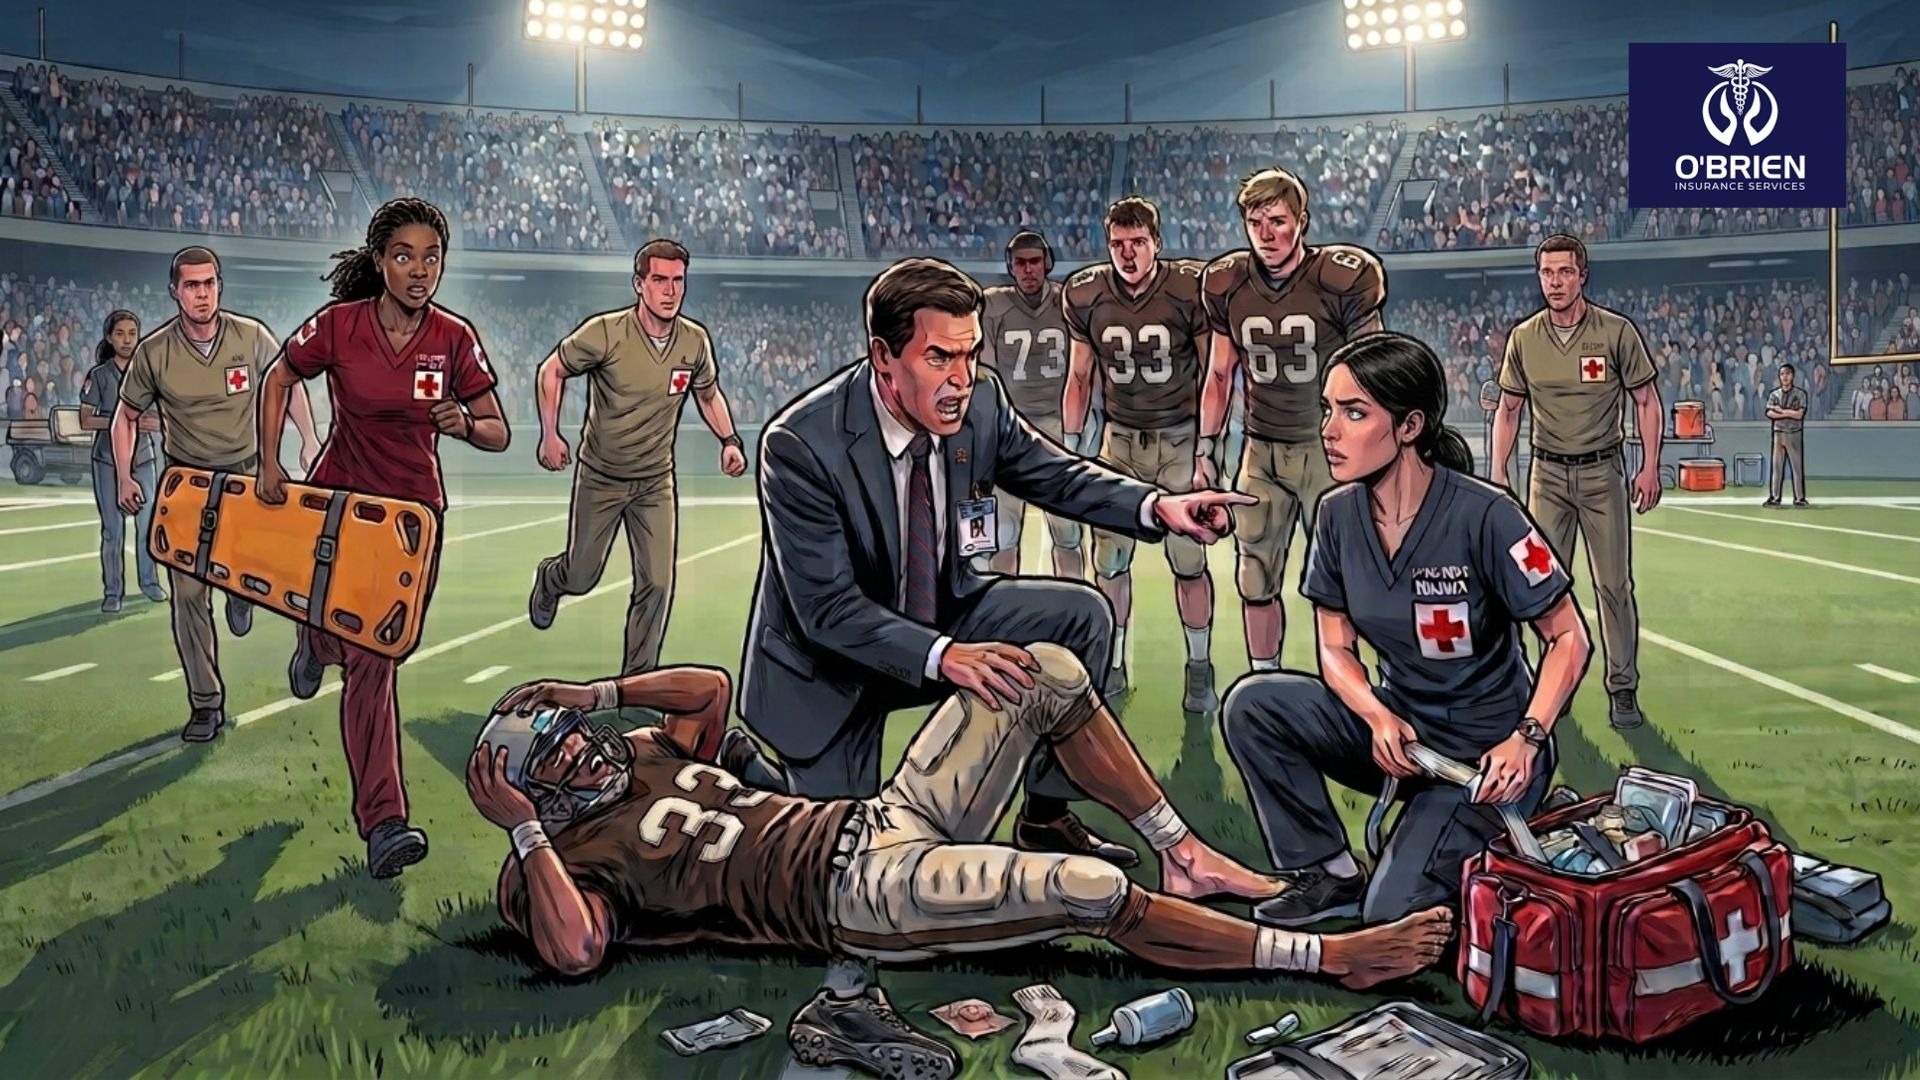
Many groups serve local employers and educational institutions, which means providing care outside the traditional clinical setting. Confirm that your medical professional liability coverage addresses these external relationships with different lines of work.
Malpractice insurance for regenerative medicine and stem cell therapy is among the fastest-evolving areas of liability, and traditional policies may not fully address it. The American Board of Medical Specialties (ABMS) compliance matters here. Treatments should meet established guidelines, with proper informed consent, documentation, and follow-up. Carriers with expertise in this field can provide the specialized coverage these services require.
On-site team physician sports medicine coverage for schools, colleges, and professional teams creates unique exposure, from acute injury management to return-to-play decisions. This also heightens data exposure, since the injury reports, general health record of athletes, and correspondence with coaches, together widen the potential attack surface for a breach. Many practices carry just a $50,000 cyber liability limit, which is likely far too low. A single breach can exceed that in notification costs, legal fees, and regulatory fines, so it's worth re-evaluating your cyber liability coverage limits for medical practices.
Policy Mechanics: Key Terms for Orthopedics
• Claims-made policy: What matters here is timing, specifically when you file. As long as the policy is still in force at the moment a claim comes in, you're covered, even if the underlying incident happened much earlier. It's the most common structure for malpractice coverage.
• Occurrence coverage: This one flips the logic. The coverage is tied to when the incident actually took place, not when someone files a claim about it. You could cancel the policy years later and still be protected for something that happened while it was active. That extra reach comes at a higher premium.
• Extended reporting period (tail coverage): extends a claims-made policy after you cancel or retire, covering later-filed claims for incidents that occurred while it was active.
• Limits of liability (1M/3M): the standard structure is $1 million per claim and $3 million aggregate. Ensure it is a perfect fit for your practice.
• AM Best financial stability rating: reflects an insurer's ability to pay claims. Anyone better than an A- boosts confidence regarding the carrier capability.
Why Doctor-Led Insurance Matters
Doctor led medical malpractice insurance companies focus on the needs of medical practices rather than shareholder profit margins. At The Doctors' Insurance Agency, we properly insure individuals and organizations, MDs, DOs, and advanced practice clinicians, with physician-designed protections and local expertise. Working with a doctor-led insurer gets you:
• Aggressive claims handling: veteran consultants with true dedication to cases of higher exposure
• Proactive defense strategies: comprehensive employee training and innovative technology
• Practical risk management: guidance rooted in clinical experience, not just actuarial tables
Financial strength matters too. An organization with $12 billion in assets is well positioned to offer protection throughout a physician's career, and an A- AM Best financial stability rating adds another layer of assurance. When comparing carriers, ask whether 1M/3M limits are adequate for your practice, how they handle high-exposure claims, what tail coverage options exist, and whether they understand orthopedic risk.
Take Action Today!
Start by assessing your group's specific needs, then request quotes and compare coverage options. Once you understand the different coverages needed for your orthopedic practice, you can build complete protection and focus on what matters the most. Patient care.
What are you waiting for?
Contact The Doctors' Insurance Agency today to discuss your orthopedic practice medical professional liability needs. From expert witness liability insurance for doctors, or ancillary service liability insurance orthopedic clinics, we got you covered.
Your patients trust you with their health. Trust The Doctors' Insurance Agency with your practice.